
Market update
Fed & BoJ Decisions in Focus After August CPI
Key takeaways
- US inflation data drew attention ahead of the Fed’s policy meeting.
- Headline CPI rose 0.4% monthly and 3.4% annually.
- Market-implied expectations for a Fed rate increase rose after the release.
Market Wrap-up: Fed rate hike expectations rise, while USD returns to gains
Markets were unsettled in the final session of last week, with the main focus on CPI data, one of the key inflation indicators available to the Fed ahead of its policy meeting on 16 September.
According to the US Bureau of Labor Statistics (BLS), headline CPI rose 0.4% month-on-month and 3.4% year-on-year. Excluding food and energy, core CPI increased 0.3% month-on-month, above expectations for a 0.2% rise. On an annual basis, core CPI rose 2.4%, in line with forecasts.
According to the CME FedWatch Tool, traders are now pricing an 86.7% probability of a Fed rate hike at this week's policy meeting, up from 59.4% around a week earlier, before the inflation data was released.
At Jackson Hole, Wyoming, just a few weeks ago, Warsh indicated that the Fed would maintain a firm stance on inflation, following the less clear messaging from the July meeting that had left investors uncertain.
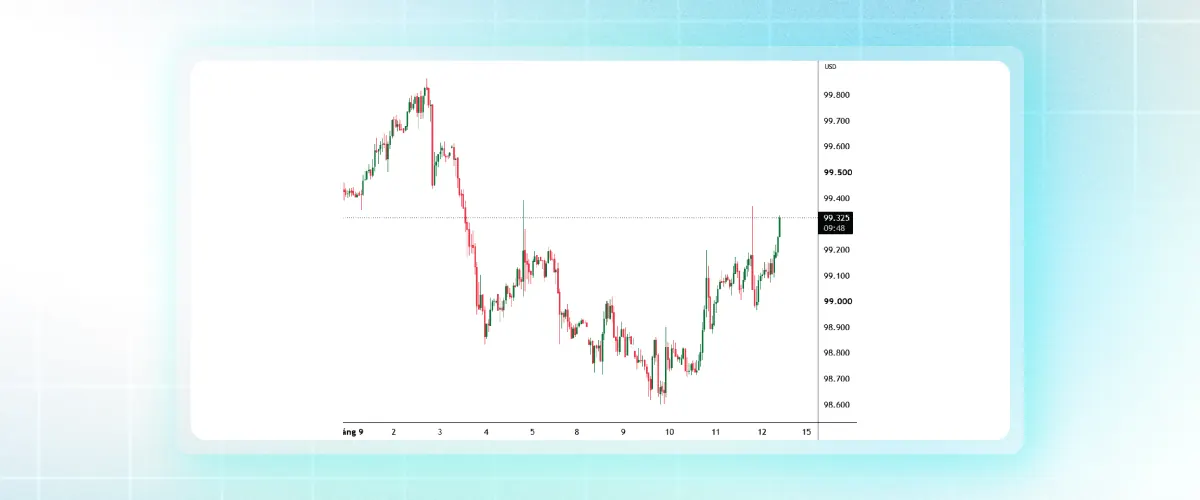
The US dollar edged higher in the final session of the week following the inflation data, but ended the week near the 99.00 level.
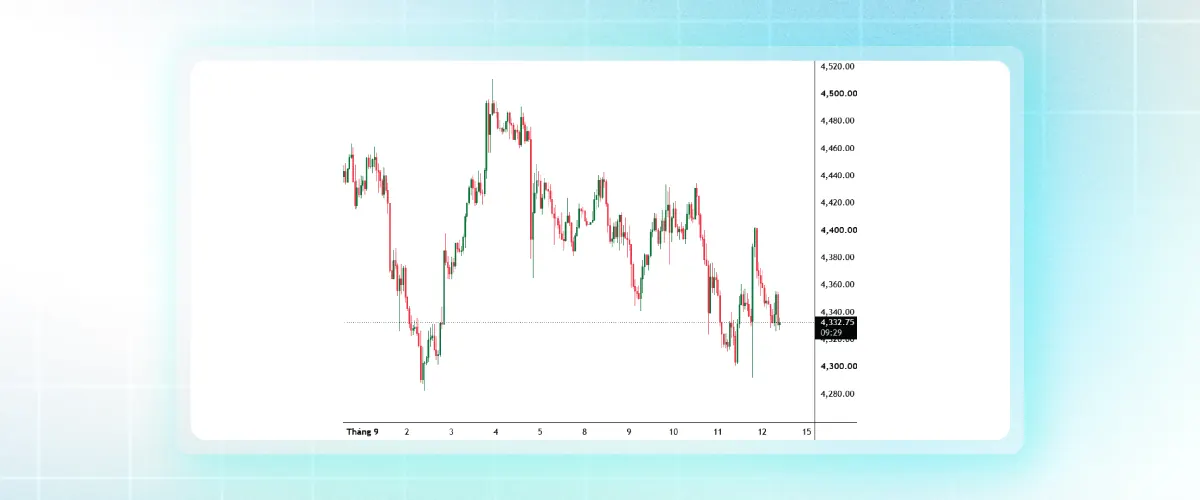
Spot gold fell around 1.5% over the week, despite rising 1.1% to $4,363.01 per ounce on Friday.
Alongside the Fed, the BoJ's meeting on Friday will also be closely watched, with markets considering the possibility of a rate hike to 1.25%, which would take Japan's policy rate to its highest level in several decades.
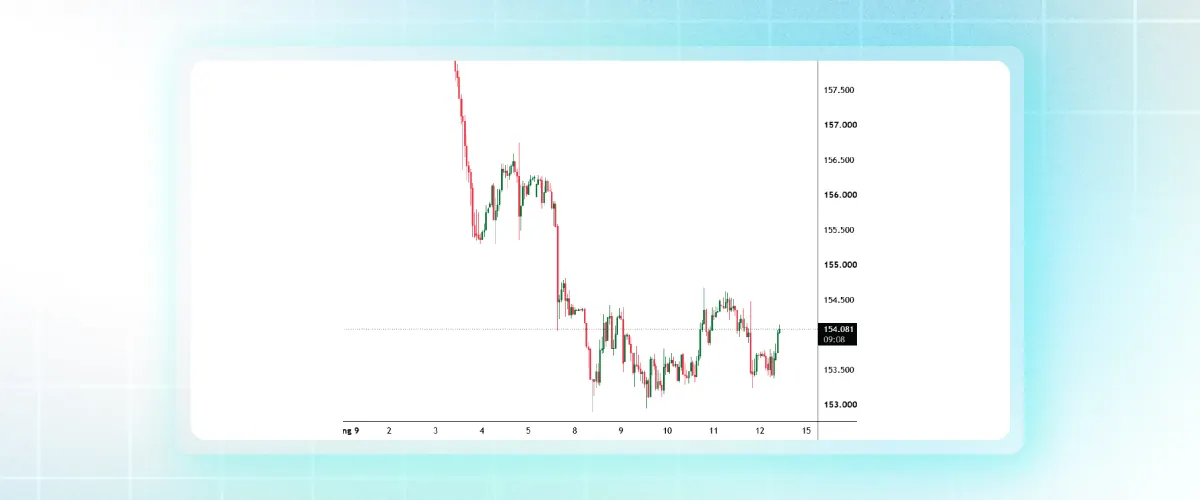
With the Fed and BoJ potentially tightening policy in the same week, expectations for further yen strength have increased. USD/JPY was trading around 154.00 in early Asian trading today.
In energy markets, Brent and WTI crude both fell by more than 2% in the final session of last week. Diplomatic efforts also remained in focus, although a planned meeting involving Iran and Gulf Arab states in Oman to discuss the Strait of Hormuz was postponed.
However, oil prices rose sharply in early Asian trading today after Saudi Arabia temporarily suspended operations on its East-West pipeline following drone attacks, disrupting an important route that bypasses the Strait of Hormuz.
The pipeline had been transporting around 4 million barrels per day to the Red Sea port of Yanbu, making it an important alternative route to the Strait of Hormuz.
Trump said the conflict would end after the US midterm elections, while also stating that oil and gas prices would decline following the key vote in November. Meanwhile, markets are assessing the possibility of a prolonged conflict involving Iran.
Against the backdrop of developments in the Middle East, The Wall Street Journal reported that senior White House advisers had discussed with President Donald Trump the possibility that the conflict could continue beyond his current term.
Looking ahead, the Fed and BoJ rate decisions will be the main focus this week. The BoE will also hold its policy meeting and is expected to keep rates unchanged at 3.75%.
ECB officials are also scheduled to speak, while upcoming US data, including the ADP Employment Change Weekly, Retail Sales and Initial Jobless Claims, will be closely monitored.
Trading Forex and CFDs involves risk. Availability and terms vary by jurisdiction and entity.
DXY:
Key takeaway:
- DXY held near 99.00, with rate expectations providing the main support.
- The Fed decision remains the key near-term catalyst.
Technical Outlook:
- Daily Bias: Bullish
- Support: 98.87
- Resistance: 99.36
Gold:
Key takeaway:
- Gold ended the week lower, despite Friday's rebound to $4,363.01.
- Higher oil prices kept inflation and interest-rate expectations in focus, while gold remained lower over the week.
Technical Outlook:
- Daily Bias: Bearish
- Support: 4,292
- Resistance: 4,434
Oil:
Key takeaway:
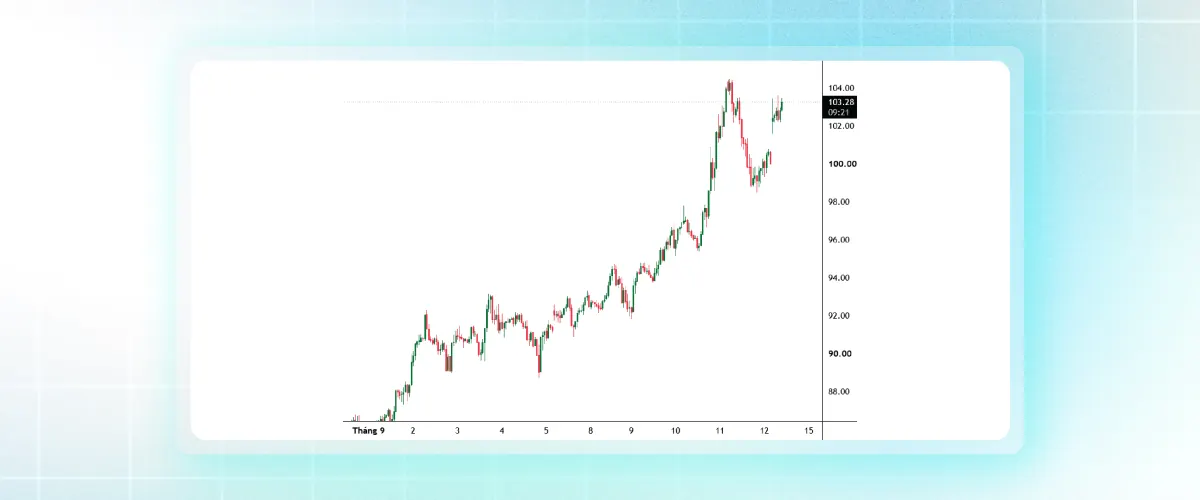
- Oil prices ended Friday lower but rebounded sharply in early Asian trading.
- Middle East developments remain the main source of near-term price risk.
Technical Outlook:
- Daily Bias: Bullish
- Support: 95.38
- Resistance: 104.47
Japanese Yen:
Key takeaway:
- USD/JPY remained around 154.00, leaving the yen sensitive to this week's central bank decisions.
- BoJ policy expectations remain the key focus for the yen.
Technical Outlook:
- Daily Bias: Bullish
- Support: 152.93
- Resistance: 154.68
Calendar Watch:
- Fed rate decision: 16 September
- BoE rate decision: 17 September
- BoJ rate decision: 18 September
- US data: ADP Employment Change Weekly, Retail Sales, Initial Jobless Claims
- ECB: Speeches from ECB officials
Whether you are new to the markets or an experienced trader, stay connected to global markets with CPT Markets.
Access our trading platforms across multiple devices, with competitive spreads and fast execution.
This content is provided for informational purposes only and does not constitute investment advice, investment recommendations, or an offer or solicitation to buy or sell any financial instrument. Trading financial products such as Forex and CFDs involves a high level of risk and may not be suitable for all investors.
You may lose all of your invested capital, and in certain circumstances, losses may exceed your initial deposit. Please ensure that you fully understand the risks involved and carefully consider your financial objectives, level of experience, and financial situation before trading.
Explore account information
Review account details, terms, and risks on the official CPT website.
Related articles
- Market update
Wall Street Faces a Double Blow From AI Fears and Rising Oil Prices
US stocks ended lower on Thursday, led by a sharp decline in technology shares as investors reassessed the outlook for AI-related spending. The Nasdaq Composite fell 2.60% to 26,008.86, recording its largest…
- Market update
Oil Rises on Saudi Attacks as Dollar Pauses and Stocks Advance
Oil prices rose on Thursday after attacks in Saudi Arabia prompted the United States to order some diplomats and family members to leave its missions in the Kingdom. Brent crude futures gained 1.2% to $110.11…
- Market update
Gold Edges Lower as Fed Rate Outlook Clouds Markets
The US dollar remained under pressure on Wednesday after falling to a three-week low in the previous session, as lower Treasury yields and crude oil prices weighed on the currency. The US Dollar Index (DXY)…