
Market update
DXY Holds Above 100; Wall Street Rebounds Ahead of Fed Speakers
Key takeaways
- US equities rebounded as major technology shares advanced.
- Lower oil prices and Treasury yields supported the recovery.
- Semiconductor stocks led technology-sector gains.
Market Wrap-up: DXY Firm, Wall Street Rebounds and Oil Falls
US equities rebounded strongly on Monday, 21 September, as major technology stocks advanced while lower oil prices and Treasury yields helped Wall Street recover from a broadly weaker previous week.
The S&P 500 rose 1.49% to 7,764.70, while the Nasdaq Composite gained 2.26% to a record 27,122.09. The Dow Jones Industrial Average increased 366.19 points, or 0.71%, to 52,048.83.
Semiconductor stocks led the technology-sector gains. Intel surged 12%, AMD rose about 10% and pushed its market capitalisation above $1 trillion, while Qualcomm gained more than 9%.
The rebound followed a weaker previous week, when the Dow Jones fell 1.7%, its worst weekly performance since March. The S&P 500 declined about 0.1%, while the Nasdaq was the only major index to finish the week higher, gaining 0.7%.
Oil prices declined sharply, with WTI crude falling 4.5% to $95.78 a barrel and Brent crude dropping 3.4% to $100.34. Brent briefly fell to $98.98 during the session. The move came as markets assessed the potential for reduced tensions following reports that US President Donald Trump was open to dialogue with Iran.
Oil markets were also assessing the impact of Saudi Arabia's East-West pipeline closure. JPMorgan analysts said Middle Eastern oil exports remained relatively resilient following the disruption, while flows from the broader Middle East had recovered to around 80% of pre-war levels, according to TD Securities' Ryan McKay.
US Treasury yields moved lower alongside oil prices. The 10-year Treasury yield fell more than 4 basis points to 4.951%, while the 30-year yield declined to 5.284%. The moves came after the Federal Reserve raised interest rates the previous week, its first rate increase in three years, amid persistent inflation concerns.
Ed Yardeni, President of Yardeni Research, said prolonged high energy prices could reinforce the case for tighter monetary policy and increase the risk of second-round inflation effects.
Jeffrey Roach, Chief Economist at LPL Financial, also highlighted the interaction between geopolitical developments, energy prices, inflation and monetary policy.
The US dollar started the week higher, recovering from two consecutive sessions of losses as markets continued to assess the prospect of further Federal Reserve tightening.
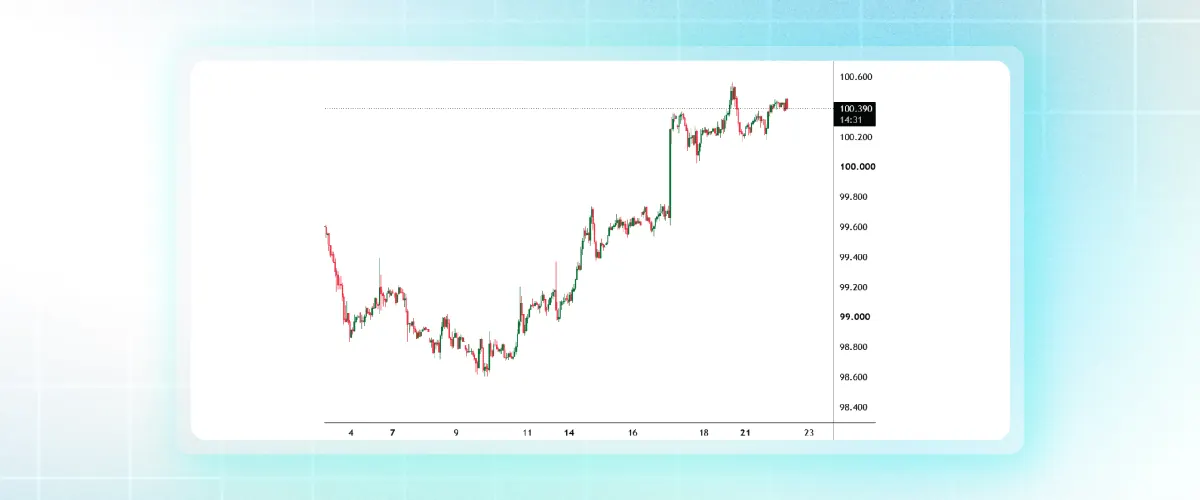
The DXY remained above the 100.00 psychological level. EUR/USD fell back below 1.1500, while USD/JPY extended its advance above 157.00.
Spot gold declined 0.6% to $4,349.94 an ounce at 2:30 a.m. ET, after briefly falling more than 1% to $4,322.19. US gold futures settled 0.9% lower at $4,383.90. A firmer US dollar and expectations of further Fed tightening weighed on the precious metal.
Markets will now focus on weekly US ADP employment data and speeches from Fed officials Williams, Jefferson and Barkin. Attention will also turn to developments in the Middle East and potential diplomatic engagement between the US and Iran.
Trading Forex and CFDs involves risk. Availability and terms vary by jurisdiction and entity.
DXY:
Key takeaway:
- DXY held above 100.00 as expectations of further Fed tightening supported the dollar.
- The dollar regained ground after two consecutive sessions of losses.
Technical Outlook:
- Daily Bias: Bullish
- Support: 100.00
- Resistance: 100.56
Gold:
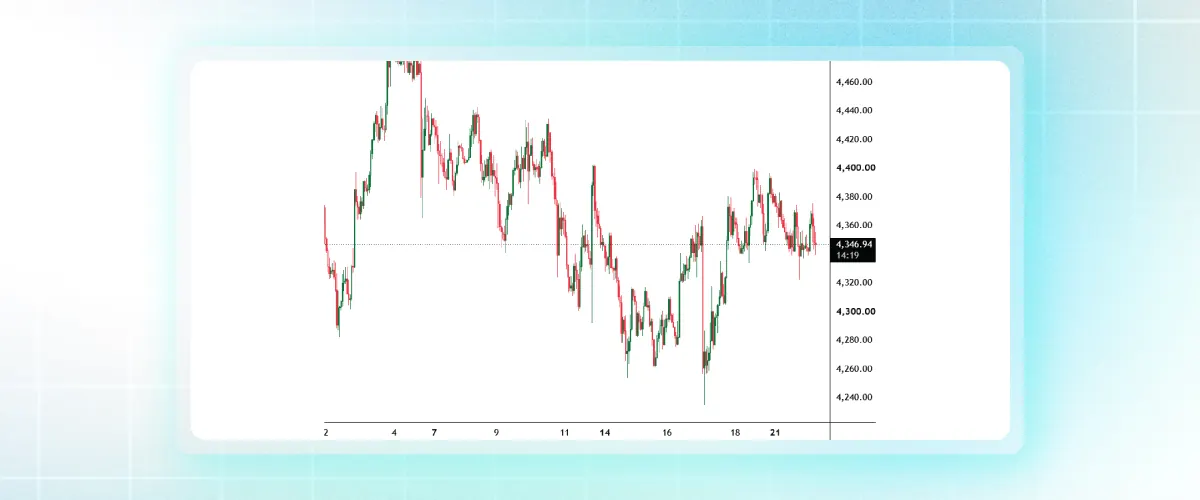
Key takeaway:
- Gold remained under pressure as a firmer dollar and higher-rate expectations reduced demand.
- Spot gold briefly fell below $4,330 before recovering from the session low.
Technical Outlook:
- Daily Bias: Bearish
- Support: 4,322
- Resistance: 4,397
Oil:
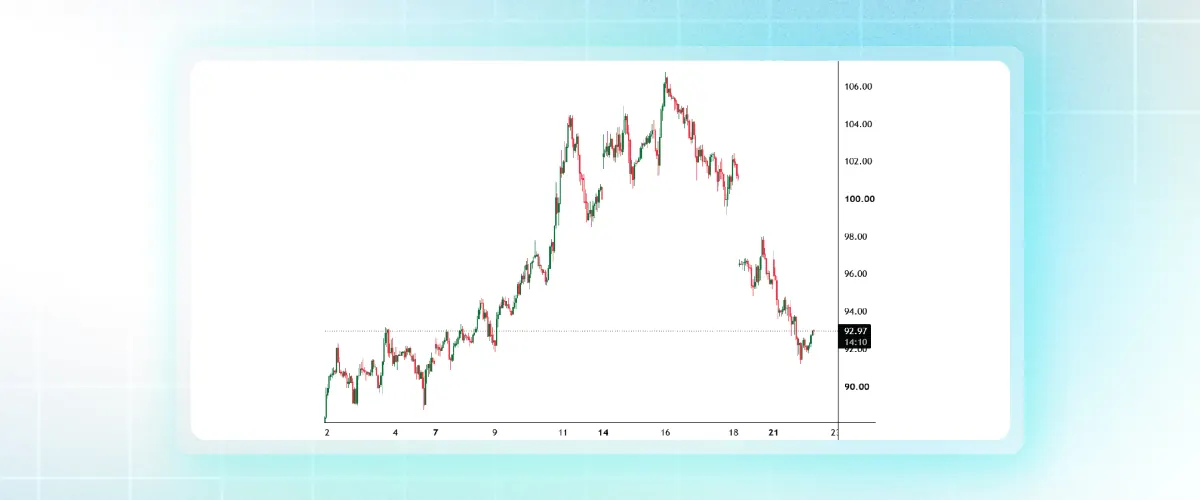
Key takeaway:
- WTI and Brent extended their declines for a fourth consecutive session.
- Resilient Middle East oil flows eased some concerns over the scale of the supply disruption.
Technical Outlook:
- Daily Bias: Bearish
- Support: 91.22
- Resistance: 98.00
Dow Jones:
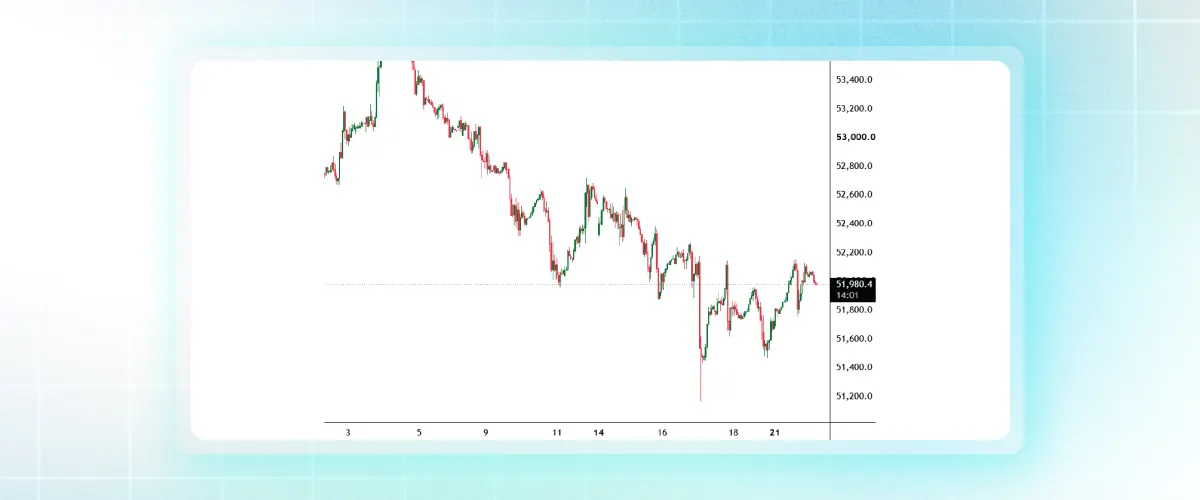
Key takeaway:
- The Dow rebounded after its weakest weekly performance since March.
- The index gained 366.19 points as technology stocks led the broader Wall Street recovery.
Technical Outlook:
- Daily Bias: Bearish
- Support: 51,167
- Resistance: 52,274
Calendar Watch:
- US: ADP Employment Change - The latest private-sector employment data will provide a further indication of labour-market conditions.
- US: Fed officials Williams, Jefferson and Barkin - Markets will monitor their comments for further guidance on monetary policy.
- Eurozone: ECB official Buch's speech and preliminary Consumer Confidence - Investors will assess the latest comments from the ECB and the preliminary consumer-confidence reading.
Whether you are new to the markets or an experienced trader, stay connected to global markets with CPT Markets.
Access our trading platforms across multiple devices, with competitive spreads and fast execution.
This content is provided for informational purposes only and does not constitute investment advice, investment recommendations, or an offer or solicitation to buy or sell any financial instrument. Trading financial products such as Forex and CFDs involves a high level of risk and may not be suitable for all investors.
You may lose all of your invested capital, and in certain circumstances, losses may exceed your initial deposit. Please ensure that you fully understand the risks involved and carefully consider your financial objectives, level of experience, and financial situation before trading.
Explore account information
Review account details, terms, and risks on the official CPT website.
Related articles
- Market update
Wall Street Faces a Double Blow From AI Fears and Rising Oil Prices
US stocks ended lower on Thursday, led by a sharp decline in technology shares as investors reassessed the outlook for AI-related spending. The Nasdaq Composite fell 2.60% to 26,008.86, recording its largest…
- Market update
Oil Rises on Saudi Attacks as Dollar Pauses and Stocks Advance
Oil prices rose on Thursday after attacks in Saudi Arabia prompted the United States to order some diplomats and family members to leave its missions in the Kingdom. Brent crude futures gained 1.2% to $110.11…
- Market update
Gold Edges Lower as Fed Rate Outlook Clouds Markets
The US dollar remained under pressure on Wednesday after falling to a three-week low in the previous session, as lower Treasury yields and crude oil prices weighed on the currency. The US Dollar Index (DXY)…