
Market update
Dollar Recovers, Yen Holds Steady as Gold and Oil Slip
Key takeaways
- The dollar recovered after a two-day losing streak.
- The pound and Australian dollar edged higher while the euro held steady.
- French political uncertainty widened the French-German government bond yield gap.
Market Wrap-Up: Dollar Recovers as Gold Slips and Oil Falls
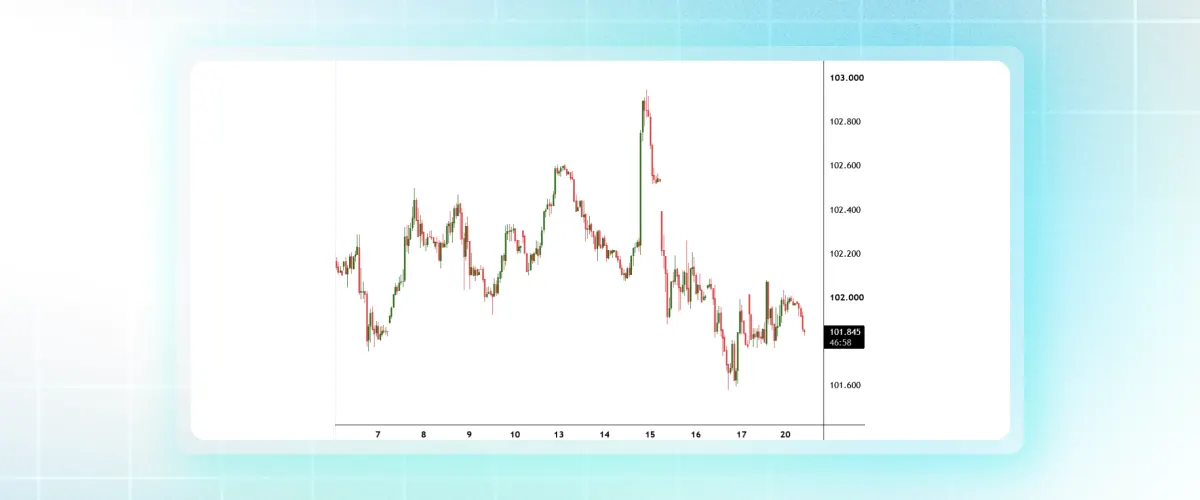
The DXY rose 0.2% to 101.98 in the previous session, ending a two-day losing streak. In early Asian trading on Tuesday, 20 October, the US dollar traded broadly sideways as higher-yielding currencies gained modestly amid an improvement in risk appetite.
The euro held at $1.1216, while the British pound and Australian dollar each gained 0.1% to $1.3308 and $0.6986, respectively. The New Zealand dollar also rose 0.1% to $0.5668. The yen held at 158.56 per dollar ahead of an auction of 20-year Japanese government bonds.
Meanwhile, the spread between French and German 10-year government bonds widened by 9.9 basis points to 147.3 basis points amid renewed political uncertainty in France. The US 10-year Treasury yield remained flat at 5.131%.
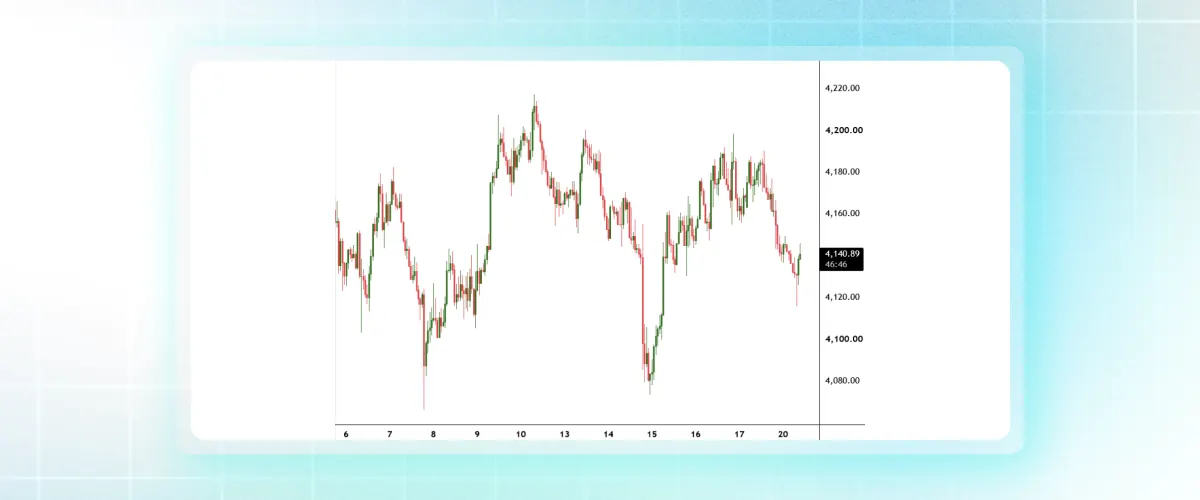
Gold edged lower as investors assessed the Federal Reserve’s policy outlook ahead of its 27-28 October meeting and the upcoming US Personal Consumption Expenditures (PCE) inflation report. Spot gold fell 0.3% to $4,126.84 an ounce, while US gold futures for December delivery declined 0.3% to $4,146.00.
According to the CME FedWatch Tool, traders were pricing in an 83% probability that the Fed would leave rates unchanged at its October meeting, while expectations for a December rate hike remained elevated at 94%.
In Japan, Bank of Japan (BOJ) Governor Kazuo Ueda said underlying inflation was quite close to the central bank's 2% target, citing strong global demand for artificial intelligence and a tight labour market as inflationary pressures. His comments signalled scope for further rate increases.
Oil prices fell in early Asian trading on Tuesday as markets assessed a US executive order waiving some sanctions and tariffs related to Russian energy exports, while renewed Houthi attacks on Saudi targets sustained concerns over Middle East supply disruptions.
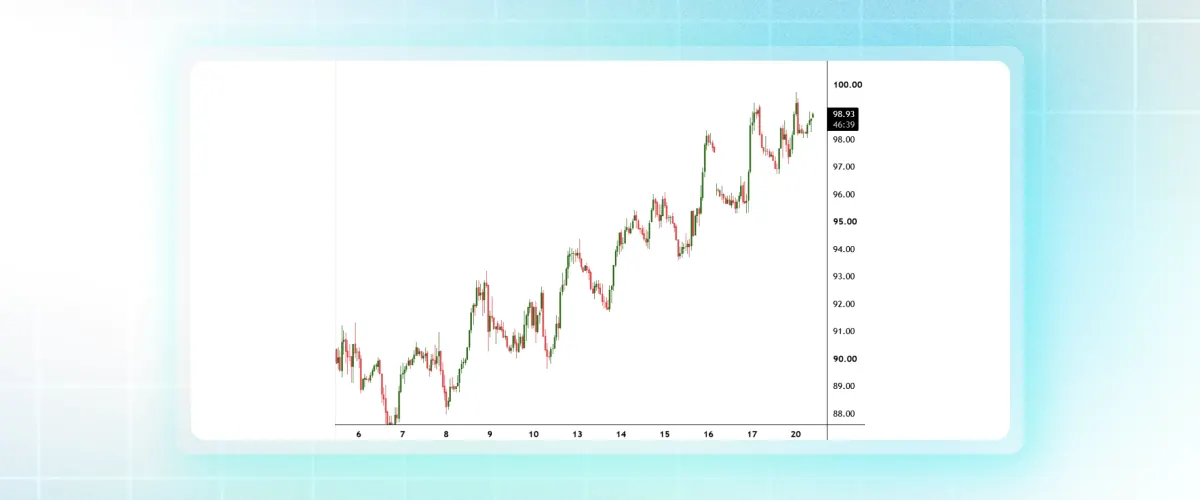
Brent crude futures fell 0.45% to $109.06 a barrel, while US West Texas Intermediate (WTI) crude futures for November delivery eased 0.33% to $103.32. The November contract was due to expire on Tuesday, while the more actively traded December contract fell 0.47% to $98.08 a barrel. In the previous session, Brent had risen to $110.70, its highest level since 20 May.
The reported US waiver raised the prospect of additional Russian fuel supplies, although uncertainty remained over its implementation and duration. Secretary of State Marco Rubio said officials needed more time to assess the situation.
Russia’s crude oil production increased by 65,000 barrels per day in September to 8.43 million barrels per day, according to the International Energy Agency, but remained around 870,000 barrels per day below the level recorded a year earlier.
Meanwhile, Yemen’s Iran-aligned Houthis claimed attacks on Saudi energy, airport, and military targets, including an Aramco site in Yanbu. Saudi authorities had not immediately confirmed the claims, and Reuters could not independently verify them. The renewed attacks heightened concerns over regional stability and the potential for further energy supply disruptions.
Markets will continue to assess Middle East developments, regional oil flows, and the potential impact of the US waiver on Russian energy exports. In Europe, attention will remain on political uncertainty in France and its implications for the euro and sovereign bond markets.
For the US dollar, upcoming employment and housing data will provide further insight into economic momentum ahead of the Federal Reserve’s policy decision.
Trading Forex and CFDs involves risk. Availability and terms vary by jurisdiction and entity.
DXY
Key Takeaways
· Improved risk appetite supported higher-yielding currencies, limiting the dollar’s advance.
· Expectations for the Fed’s October decision and upcoming US economic data kept monetary policy in focus.
Technical Outlook
· Daily Bias: Bullish
· Support: 101.76
· Resistance: 102.25
Gold
Key Takeaways
· Diverging expectations for the Fed’s October and December decisions kept the interest-rate outlook uncertain.
· Anticipation of the upcoming US PCE inflation report kept attention on the data that could influence expectations for future rate decisions.
Technical Outlook
· Daily Bias: Bearish
· Support: 4,115
· Resistance: 4,190
WTI CFD
Key Takeaways
· Renewed Houthi attacks on Saudi targets heightened concerns over potential disruptions to Middle East energy supplies.
· Uncertainty over the US waiver on Russian energy exports limited clarity on the outlook for global oil supply.
Technical Outlook
· Daily Bias: Bullish
· Support: 96.71
· Resistance: 100.00
EUR/USD
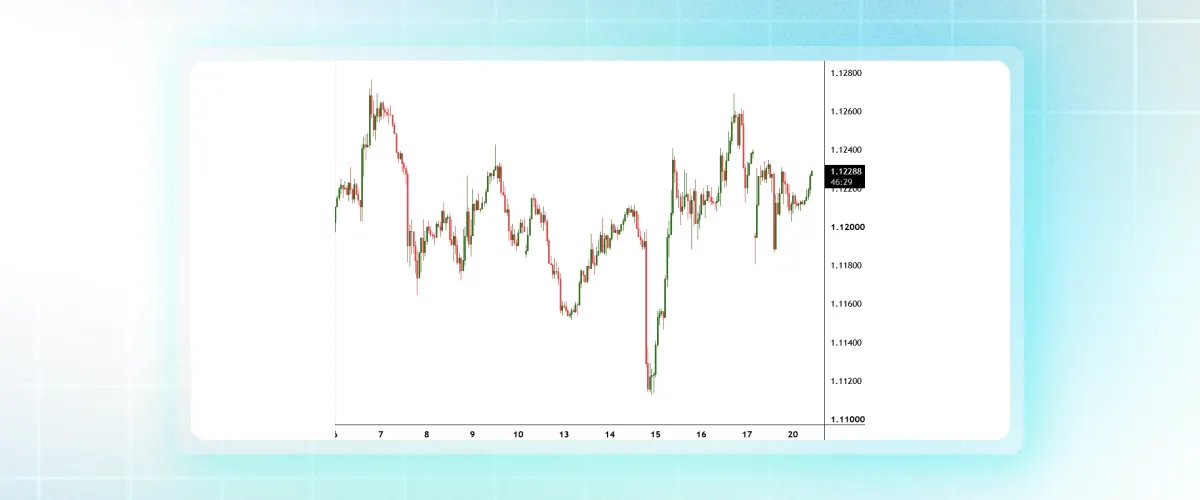
Key Takeaways
· French political uncertainty widened the government bond spread over Germany, highlighting renewed sovereign-risk concerns.
· The euro remained resilient despite wider French-German yield spreads, suggesting limited immediate spillover into the broader currency market.
Technical Outlook
· Daily Bias: Bearish
· Support: 1.11800
· Resistance: 1.12400
USD/JPY
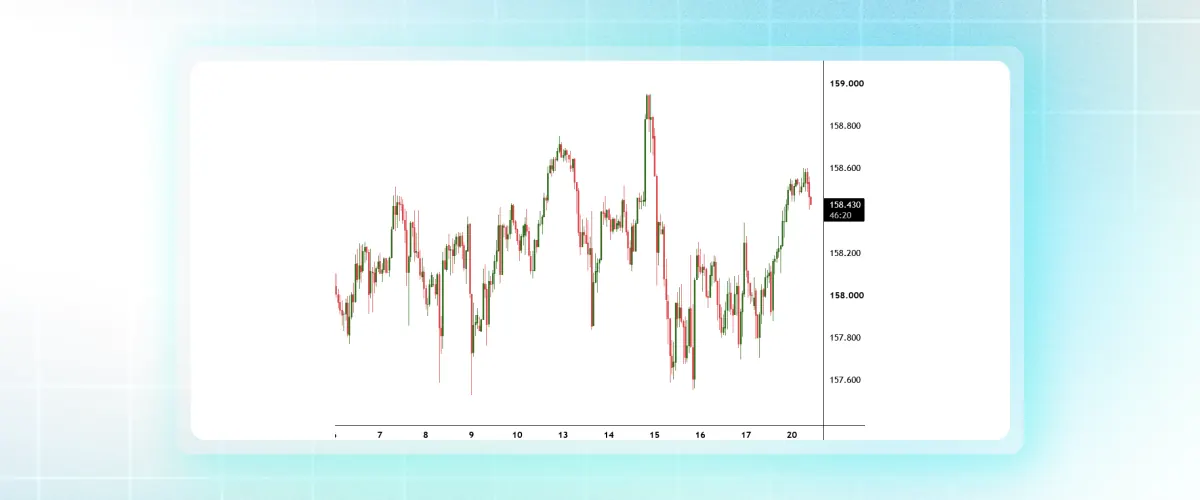
Key Takeaways
· The BOJ’s assessment of underlying inflation left scope for further policy tightening, potentially supporting the yen.
· The upcoming Japanese government bond auction kept domestic bond-market demand in focus.
Technical Outlook
· Daily Bias: Bullish
· Support: 157.70
· Resistance: 158.60
Calendar Watch
· ADP Employment Change Weekly: Markets will assess the latest private-sector employment trend for fresh insight into labour-market conditions and potential implications for the Federal Reserve’s policy outlook.
· Housing Starts: The report will provide insight into residential construction activity, helping markets assess housing-sector momentum amid elevated borrowing costs.
· Pending Home Sales MoM & YoY: The data will offer a forward-looking gauge of existing-home sales demand, with monthly and annual changes helping markets assess housing-market momentum and affordability pressures.
Whether you are new to the markets or an experienced trader, stay connected to global markets with CPT Markets.
Access our trading platforms across multiple devices, with competitive spreads and fast execution.
This content is provided for informational purposes only and does not constitute investment advice, investment recommendations, or an offer or solicitation to buy or sell any financial instrument. Trading financial products such as forex and CFDs involves a high level of risk and may not be suitable for all investors.
You may lose all of your invested capital, and in certain circumstances, losses may exceed your initial deposit. Please ensure that you fully understand the risks involved and carefully consider your financial objectives, level of experience, and financial situation before trading.
Explore account information
Review account details, terms, and risks on the official CPT website.
Related articles
- Market update
Wall Street Faces a Double Blow From AI Fears and Rising Oil Prices
US stocks ended lower on Thursday, led by a sharp decline in technology shares as investors reassessed the outlook for AI-related spending. The Nasdaq Composite fell 2.60% to 26,008.86, recording its largest…
- Market update
Oil Rises on Saudi Attacks as Dollar Pauses and Stocks Advance
Oil prices rose on Thursday after attacks in Saudi Arabia prompted the United States to order some diplomats and family members to leave its missions in the Kingdom. Brent crude futures gained 1.2% to $110.11…
- Market update
Gold Edges Lower as Fed Rate Outlook Clouds Markets
The US dollar remained under pressure on Wednesday after falling to a three-week low in the previous session, as lower Treasury yields and crude oil prices weighed on the currency. The US Dollar Index (DXY)…