
Market update
Dollar Holds Firm as October Fed Hike Bets Fade
Key takeaways
- Softer US employment data reduced expectations for further Fed tightening.
- September payroll gains fell short of forecasts, and August figures were revised lower.
- Stock futures rose and bonds steadied as October rate-hike expectations eased.
Market Wrap-Up: Softer NFP Data Dims October Fed Hike Bets
US stock futures started Monday higher and bonds steadied as traders reduced expectations for an aggressive Federal Reserve tightening cycle following weaker-than-expected US employment data. The dollar nevertheless held firm near a 17-month high, supported in part by continued weakness in the euro.
US employers added 29,000 jobs in September, well below economists’ 90,000 forecast, while August payroll gains were revised lower. The unemployment rate rose to 4.2% from 4.1%, alongside an increase in labour-force participation, while wage growth also slowed.
The softer labour data has reduced expectations for another rate increase at the Fed's October 27-28 meeting. Traders were pricing in a 22% probability of an October hike on Monday, down from 64% a week earlier, according to the CME FedWatch Tool.
Fed policymakers have also signalled a preference for more data before taking further action. Chicago Fed President Austan Goolsbee said there was room for either a rate increase or a pause, while noting that inflation remained the main problem for the central bank.
US Treasury yields eased slightly, with the 10-year yield at 5.2643% and the two-year yield at 4.8143%. Yields remained near multi-year highs as bond markets continued to face pressure from government financing needs, heavy issuance and elevated energy costs.
The dollar held firm near a 17-month high despite reduced expectations for an October Fed rate hike. The euro remained under pressure near $1.1246, while sterling stood at $1.3241 and the dollar traded around 157.69 against the yen.
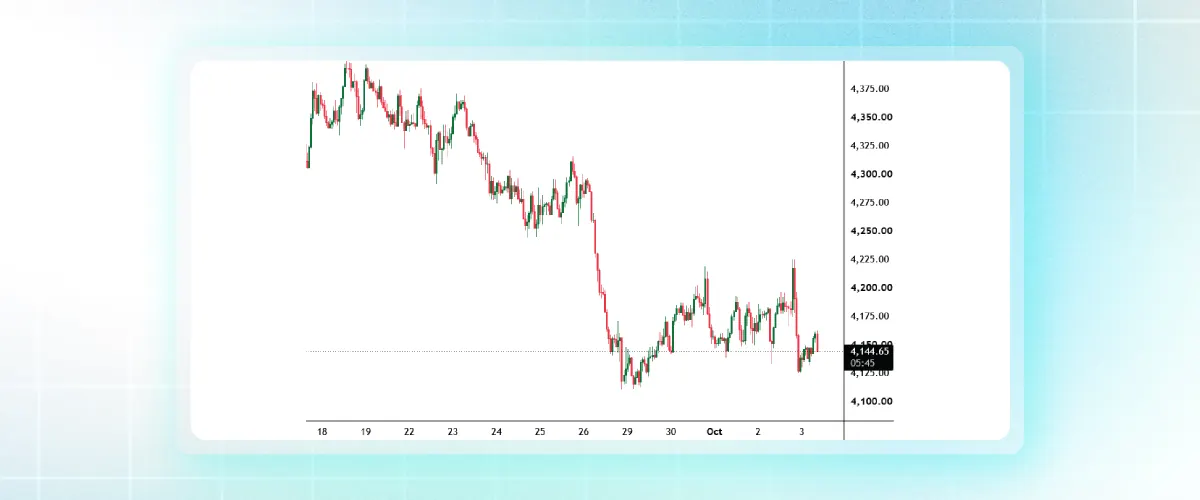
Gold benefited from the lower October rate-hike expectations, Reuters reported spot gold up 0.4% at $4,158.17 per ounce by 01:50 GMT, while December US gold futures rose 0.6% to $4,186.40.
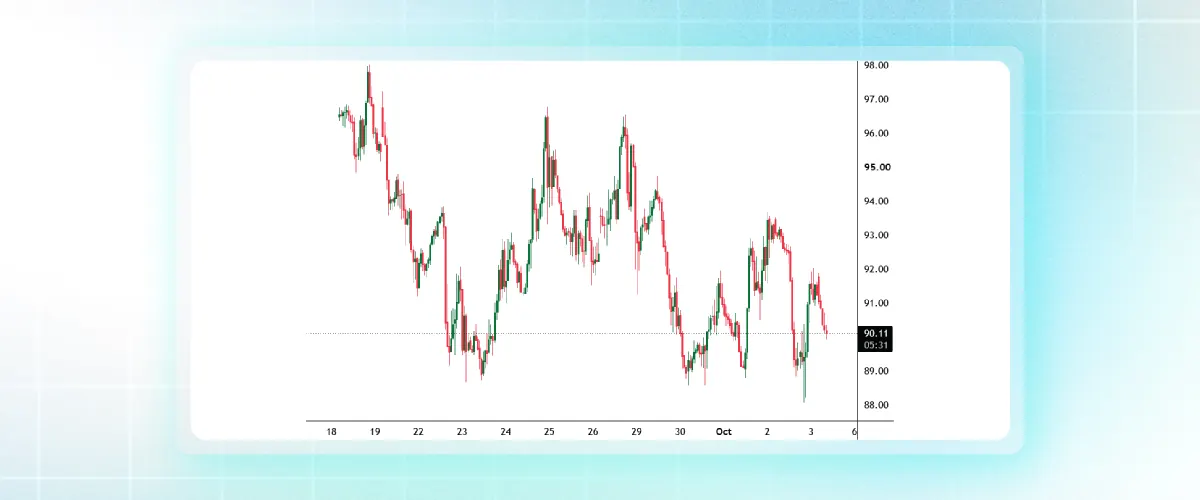
Oil prices edged lower but remained elevated as increased Middle East crude exports and the G7’s planned release of emergency reserves offset concerns over regional tensions. Brent crude futures traded at $101.59 a barrel, while WTI stood at $90.12. Yemen’s Saudi-backed government has launched a major military campaign against the Iran-backed Houthis, keeping geopolitical supply risks in focus.
Markets will now turn to this week’s economic data and Fed communications for further clues on the rate outlook, while developments in energy markets and geopolitics could continue to influence inflation expectations and broader risk sentiment ahead of the Fed’s late-October meeting.
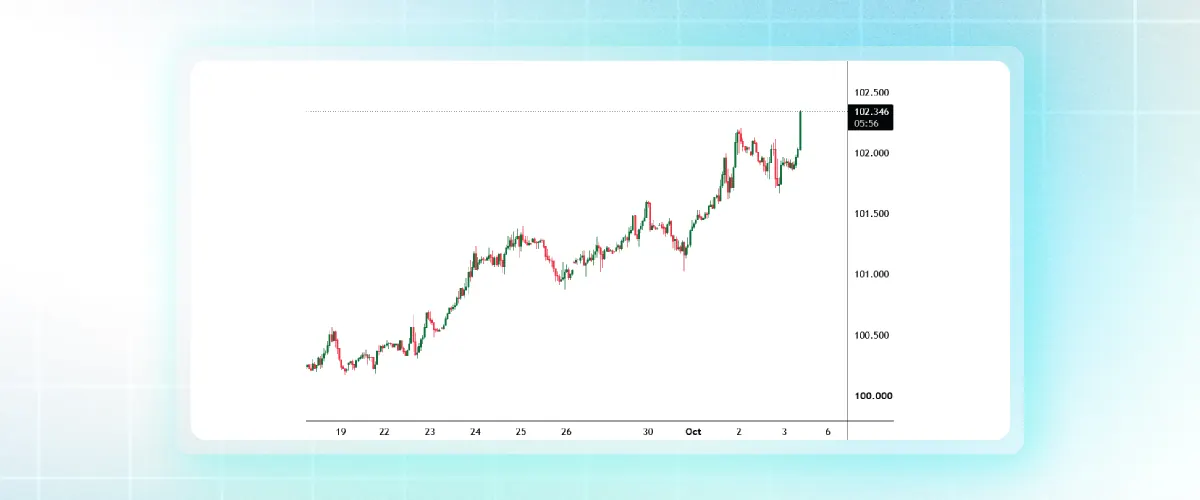
DXY:
Key takeaway:
- The dollar held firm despite fading expectations for an October Fed rate hike.
- The dollar remained near a 17-month high as markets reassessed the Fed’s policy path.
Technical Outlook:
- Daily Bias: Cautiously Bullish
- Support: 101.67
- Resistance: 102.60
Trading Forex and CFDs involves risk. Availability and terms vary by jurisdiction and entity.
XAU/USD:
Key takeaway:
- Gold retained support as expectations for an October Fed hike eased.
- Oil prices and Middle East developments remained relevant to the gold outlook.
Technical Outlook:
- Daily Bias: Cautiously Bearish
- Support: 4,111
- Resistance: 4,225
WTI:
Key takeaway:
- Crude remained elevated amid ongoing Middle East supply concerns.
- The G7’s coordinated emergency stock release will remain an important development for the oil market.
Technical Outlook:
- Daily Bias: Bearish
- Support: 88.08
- Resistance: 93.68
Dow Jones:
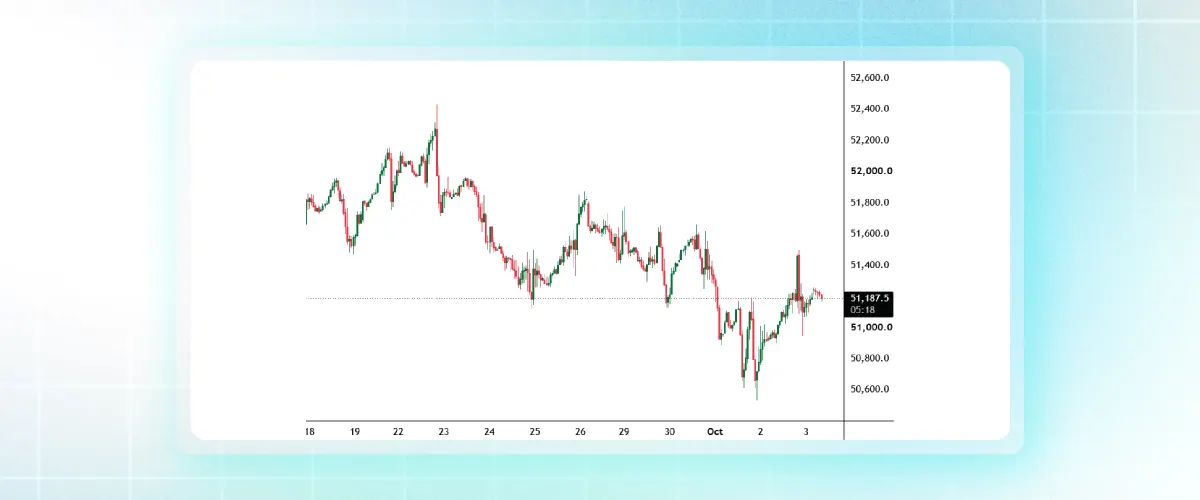
Key takeaway:
- US stock futures moved higher as markets reassessed the outlook for monetary policy.
- Softer US labour-market data improved the near-term rate outlook for equities.
Technical Outlook:
- Daily Bias: Bullish
- Support: 50,946
- Resistance: 51,493
Calendar Watch:
- ISM Services PMI (Monday, 5 October): The services data will provide further signals on the health of the US economy following weaker-than-expected NFP data.
- FOMC Minutes (Wednesday, 7 October): The September meeting minutes could provide further insight into the Fed’s concerns over inflation and the labour market, influencing rate expectations.
- Initial Jobless Claims (Thursday, 8 October): Markets will continue to monitor fresh signals on labour-market conditions following the September NFP report.
- Preliminary University of Michigan Consumer Sentiment (Friday, 9 October): The data will draw attention as energy prices and inflation continue to weigh on the consumer outlook.
- Middle East & Oil Markets: Developments in the Middle East and the G7’s coordinated release of 100 million barrels from emergency energy reserves will remain important factors for crude oil prices, inflation expectations, and broader risk sentiment.
Whether you are new to the markets or an experienced trader, stay connected to global markets with CPT Markets.
Access our trading platforms across multiple devices, with competitive spreads and fast execution.
This content is provided for informational purposes only and does not constitute investment advice, investment recommendations, or an offer or solicitation to buy or sell any financial instrument. Trading financial products such as Forex and CFDs involves a high level of risk and may not be suitable for all investors.
You may lose all of your invested capital, and in certain circumstances, losses may exceed your initial deposit. Please ensure that you fully understand the risks involved and carefully consider your financial objectives, level of experience, and financial situation before trading.
Explore account information
Review account details, terms, and risks on the official CPT website.
Related articles
- Market update
Wall Street Faces a Double Blow From AI Fears and Rising Oil Prices
US stocks ended lower on Thursday, led by a sharp decline in technology shares as investors reassessed the outlook for AI-related spending. The Nasdaq Composite fell 2.60% to 26,008.86, recording its largest…
- Market update
Oil Rises on Saudi Attacks as Dollar Pauses and Stocks Advance
Oil prices rose on Thursday after attacks in Saudi Arabia prompted the United States to order some diplomats and family members to leave its missions in the Kingdom. Brent crude futures gained 1.2% to $110.11…
- Market update
Gold Edges Lower as Fed Rate Outlook Clouds Markets
The US dollar remained under pressure on Wednesday after falling to a three-week low in the previous session, as lower Treasury yields and crude oil prices weighed on the currency. The US Dollar Index (DXY)…